HOW IT ALL WORKS
The technical part explained – it’s all about cashflow
The technical part explained – it’s all about cashflow
You’ve invested in property to make money.
Making sure eligible assets are correctly identified and valued is one part of achieving that.
Valuit has developed a straightforward process to help residential property investors obtain the valuation information their accountants need.
We take care of the specialist valuation work so you don’t have to.
Start by providing some basic information about your investment property.
We’ll establish the relevant property details, consider the type of assessment required and explain the next steps.
If you’re unsure whether a depreciation assessment would be worthwhile, contact us.
We can help you understand what the service involves before you proceed.
Our trained property inspectors identify and record the relevant assets within your investment property.
Depending on the property and the assessment requirements, this may involve an onsite inspection.
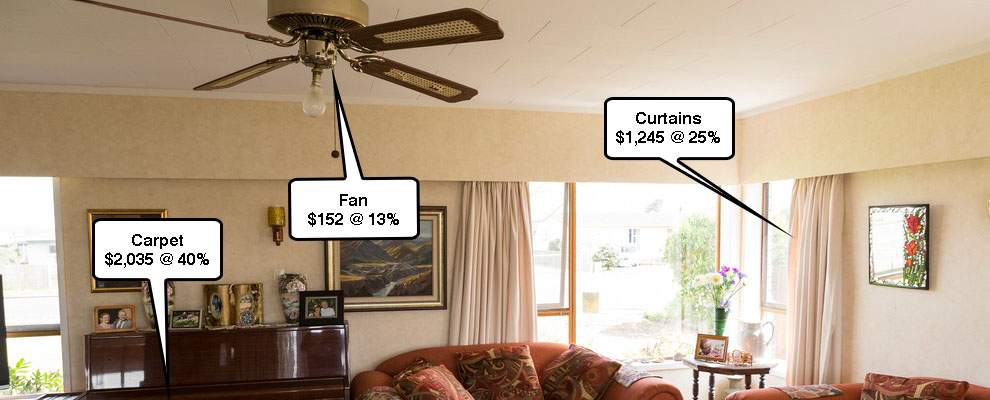
We’re looking beyond the building itself to identify assets that may qualify for separate depreciation treatment.
This can include appliances, floor coverings, window furnishings, heating equipment and other qualifying property assets.
Once the property information has been collected, our specialist valuation system is used to assess and calculate the relevant asset values.
The assessment considers the assets identified, their characteristics and the appropriate valuation methodology.
Our established processes include review and quality assurance to support consistency and accuracy.
We prepare a report identifying the assessed assets and their values.
The report provides your accountant with information to help determine the applicable depreciation deductions.
You retain the report as part of your property’s financial records.
Your accountant applies the relevant depreciation rates and tax rules to your circumstances.
Depending on your property’s financial position, the deductions may reduce current taxable income or contribute to losses available for future use, subject to the applicable rules.
The timing and amount of any tax benefit will depend on your individual circumstances.
The valuation establishes the asset information. Your accountant determines the tax treatment.
The IRD allows you to run your investment property as a business. This means that you can claim the expenses incurred against the income received for it, in order to reduce tax liability.
Depreciation is an expense that can be claimed to reduce taxable income.
Let’s have a look at an example of how depreciation can improve your cashflow:
| Rental income of $400 /week | $20,800 |
| Less cash expenses (insurance, rates, etc) | 5,000 |
| Income before depreciation (cash in your pocket) | 15,800 |
| Less Non-cash expense (depreciation) | 5,000 |
| Taxable income after depreciation (what the IRD taxes you on) | $10,800 |
Using this example, you can see that the end result will be that less tax is paid on the income received once depreciation is claimed.
Note that the actual amount of tax paid will depend on the type of ownership structure that is in place for the property, as well as other factors such as if the property has been purcahsed as a new build etc. Speak with your Lawyer and Accountant to make sure you have a structure in place that best suits your personal situation.
For years, residential property investors were able to use losses on rental properties to offset their personal tax.
Residential rental properties are often “negatively” geared. This means that the expenditure, including non-cash expenses such as interest and depreciation, exceeds the income, resulting in a loss.
The government introduced the ring-fencing of these losses, therefore preventing investors from using any losses against their personal tax.
The removal of the ability to claim the “Mortage Interest” as an expense will reduce the number of properties that are negativly geared.
At its most basic, for any property that does incur a loss, any losses are now carried over to the next income year. The losses won’t be able to be utilised until the investment makes a profit.
If the property is negatively geared for tax it will simply mean that the cashflow benefit is deferred. So it is simply a timing change.
Here are some common questions residential property investors ask about depreciation assessments.
You may still benefit from having your property’s depreciable assets assessed.
Whether deductions can be claimed for previous years depends on the applicable tax rules, the records available and your circumstances.
We can discuss the valuation requirements, while your accountant can advise on the tax treatment of earlier years.
Generally, a depreciation assessment establishes the relevant asset values at a particular point in time.
Your accountant can use those values when preparing depreciation schedules for subsequent years.
A further assessment may be appropriate if there are significant additions, alterations or other changes to the property.
You may still have qualifying depreciable assets.
A rental loss does not necessarily remove the relevance of depreciation.
However, residential rental loss ring-fencing and other tax rules can affect when deductions provide a financial benefit.
Your accountant can advise how those rules apply to your investment.
Depreciation is one part of the financial performance of your property investment.
Valuit helps you establish the information needed to account for it properly.
To see EXAMPLES or to use our CALCULATOR simply click here